2026 Inflation Outlook: Protect US Savings from 4% Erosion
Anúncios
The 2026 inflation outlook in the US economy projects a 4% erosion in savings, necessitating strategic financial planning to preserve purchasing power and secure future financial stability.
Anúncios
The prospect of a 2026 inflation outlook projecting a 4% erosion in the US economy’s savings is a critical concern for every American. Understanding this potential financial landscape and equipping yourself with effective strategies is not just prudent, it’s essential for safeguarding your hard-earned money and ensuring your financial well-being.
Understanding the 2026 Inflation Outlook
The anticipated 4% inflation rate for 2026 in the United States is more than just a number; it represents a significant challenge to the purchasing power of your savings. Inflation, at its core, is the rate at which the general level of prices for goods and services is rising, and consequently, the purchasing power of currency is falling. A 4% erosion means that what costs $100 today might cost $104 in 2026, effectively reducing the value of your stored wealth.
Anúncios
Several factors contribute to this projected inflation. Global supply chain disruptions, lingering effects of pandemic-era fiscal policies, geopolitical tensions, and shifts in consumer demand all play a role. The Federal Reserve’s monetary policy decisions, particularly regarding interest rates, also heavily influence inflationary pressures. Analyzing these complex interactions helps us grasp the magnitude of the challenge ahead and why proactive measures are necessary.
Key Drivers of Inflation
Understanding the forces behind inflation is crucial for predicting its trajectory and mitigating its impact. Economic models often point to a confluence of factors, both domestic and international, that could drive prices upward.
- Supply Chain Volatility: Ongoing disruptions from natural disasters, geopolitical events, and labor shortages continue to impact the availability and cost of goods.
- Fiscal and Monetary Policy: Government spending and central bank actions, such as quantitative easing, can inject liquidity into the economy, potentially leading to increased demand and higher prices.
- Energy Prices: Fluctuations in oil and gas prices have a ripple effect across all sectors, increasing production and transportation costs.
- Wage Growth: A tight labor market can lead to higher wages, which businesses often pass on to consumers through increased prices, creating a wage-price spiral.
These drivers, individually and collectively, paint a picture of an economy facing persistent inflationary pressures. The 2026 projection is not an isolated event but a continuation of trends that demand careful attention from individuals and policymakers alike. Being informed about these drivers empowers you to make more strategic financial decisions.
Assessing the Impact on Your Savings
A 4% inflation rate, while seemingly modest on an annual basis, can have a cumulative and significant impact on your long-term savings. Consider a scenario where you have $100,000 in a standard savings account earning a minimal interest rate. After one year of 4% inflation, the purchasing power of that $100,000 would effectively be reduced to $96,000. Over several years, this erosion can become substantial, jeopardizing your financial goals, whether they are retirement, a down payment on a home, or funding your children’s education.
It’s not just about the numbers; it’s about what those numbers represent in real-world terms. Essential goods and services, from groceries to healthcare, become more expensive, meaning your existing savings will buy less. This erosion disproportionately affects those on fixed incomes or those holding a large portion of their wealth in low-yield accounts. Recognizing this impact is the first step toward building a robust defense for your financial future.
The Silent Tax of Inflation
Inflation is often referred to as a ‘silent tax’ because it reduces the real value of your money without any explicit government levy. This hidden cost can be particularly damaging to those who are not actively managing their investments to outpace inflation.
- Reduced Purchasing Power: Every dollar saved today will buy less in the future, diminishing the value of your retirement funds and other long-term savings.
- Erosion of Fixed Income: Retirees relying on pensions or fixed annuities find their income shrinking in real terms, making it harder to maintain their standard of living.
- Impact on Interest Rates: While central banks may raise interest rates to combat inflation, these increases often lag behind, meaning real returns on savings accounts can remain negative.
Understanding this silent erosion is crucial. It underscores the urgency of moving beyond traditional savings methods and exploring investment avenues that offer a greater chance of preserving and growing your wealth in an inflationary environment. Ignoring the impact of inflation is akin to allowing your money to slowly lose value without intervention.
Diversifying Your Investment Portfolio
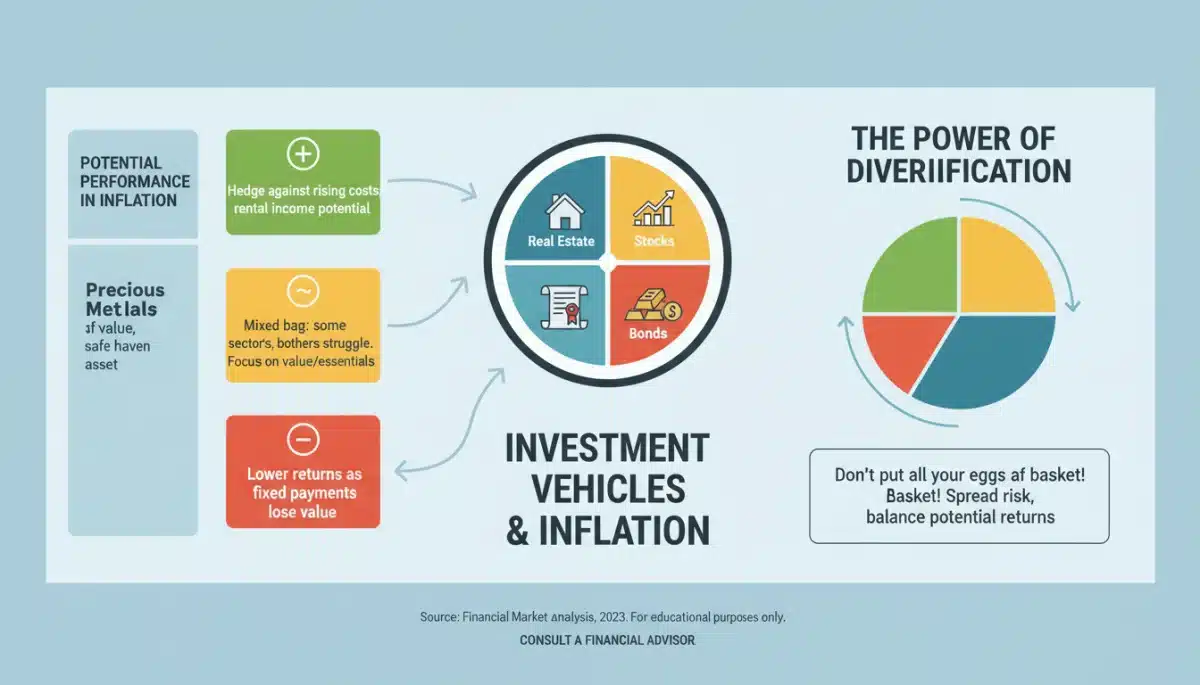
One of the most effective strategies to protect your savings from inflation is through strategic diversification of your investment portfolio. Relying solely on cash or low-interest savings accounts is a guaranteed way to see your purchasing power diminish. Instead, consider asset classes that historically perform well or offer protection during periods of inflation. The goal is to build a portfolio that can generate returns that at least match, if not exceed, the rate of inflation.
Diversification isn’t just about spreading your money across different investments; it’s about selecting assets that react differently to economic conditions. This approach helps to balance risk and reward, ensuring that if one asset class underperforms due to inflation, others might compensate. A well-constructed portfolio is your strongest ally against the erosion of wealth.
Inflation-Resistant Asset Classes
Certain asset classes have historically provided a hedge against inflation, making them attractive options for investors looking to protect their capital. These assets often derive their value from real goods or have pricing power that allows them to adjust to rising costs.
- Real Estate: Property values and rental income tend to rise with inflation, making real estate a popular hedge. This can include direct ownership or Real Estate Investment Trusts (REITs).
- Commodities: Raw materials like gold, silver, oil, and agricultural products often see their prices increase during inflationary periods. Gold, in particular, is considered a traditional safe haven.
- Inflation-Protected Securities (TIPS): These are U.S. Treasury bonds that are indexed to inflation, meaning their principal value adjusts with the Consumer Price Index (CPI), providing a guaranteed real return.
- Stocks of Companies with Pricing Power: Investing in companies that can pass on increased costs to consumers without significantly impacting demand can be beneficial. These are often established companies in essential sectors.
While no investment is entirely risk-free, allocating a portion of your portfolio to these inflation-resistant assets can significantly bolster your defense against a projected 4% erosion. A balanced approach, tailored to your risk tolerance and financial goals, is always recommended. Consulting with a financial advisor can provide personalized guidance.
Strategic Real Estate Investments
Real estate has long been regarded as a strong hedge against inflation, and for good reason. As the cost of living rises, so too do property values and rental rates. This makes real estate an attractive option for those looking to preserve and grow their wealth in an inflationary environment. Whether through direct property ownership, such as residential or commercial properties, or through more liquid avenues like Real Estate Investment Trusts (REITs), real estate offers tangible assets that tend to appreciate with rising prices.
Investing in real estate provides not only potential capital appreciation but also income generation through rent. This dual benefit can be particularly powerful during inflationary periods, as rental income can often be adjusted upwards to keep pace with rising costs. However, it’s crucial to conduct thorough due diligence, considering location, market demand, and potential maintenance costs, to ensure a sound investment.
Benefits of Real Estate in an Inflationary Environment
Real estate offers several distinct advantages that make it a compelling choice for inflation protection. Its tangible nature and income-generating potential set it apart from many other asset classes.
- Appreciation Potential: Property values typically increase with inflation, preserving and enhancing your capital’s purchasing power.
- Rental Income Growth: Landlords can often raise rents in line with inflation, providing a growing stream of income that keeps pace with rising costs.
- Leverage: Real estate allows for leverage through mortgages, enabling investors to control a significant asset with a smaller upfront capital outlay.
- Tax Advantages: Many real estate investments offer tax benefits, such as depreciation deductions, which can further enhance returns.
While real estate can be illiquid and requires significant capital, its ability to generate both income and capital appreciation makes it a cornerstone of an inflation-resistant portfolio. Exploring various real estate investment options, from direct ownership to publicly traded REITs, can help tailor this strategy to your specific needs and risk appetite.
Exploring Alternative Investments
Beyond traditional stocks, bonds, and real estate, a range of alternative investments can offer additional protection against inflation and further diversify your portfolio. These options often have a lower correlation with conventional markets, providing a buffer during economic downturns or periods of high inflation. Precious metals, commodities, and even certain types of private equity can serve as valuable hedges, helping to preserve your capital’s purchasing power when traditional assets falter.
However, alternative investments often come with higher risks and lower liquidity, requiring a deeper understanding and careful consideration. It’s essential to research each option thoroughly and understand its specific characteristics before committing capital. The goal is to strategically allocate a portion of your wealth to these assets to enhance your overall portfolio’s resilience against inflationary pressures.
Precious Metals and Commodities
Precious metals, particularly gold and silver, have historically served as stores of value during times of economic uncertainty and inflation. Their intrinsic value is not tied to any single currency or government, making them attractive safe havens.
- Gold: Often considered the ultimate inflation hedge, gold tends to perform well when confidence in fiat currencies declines.
- Silver: While more volatile than gold, silver has industrial demand in addition to its monetary role, which can boost its value during economic expansion.
- Commodities: Investing in a broad basket of commodities, such as energy, agriculture, and industrial metals, can also offer inflation protection as their prices generally rise with increasing demand and production costs.
These investments can be accessed through physical holdings, exchange-traded funds (ETFs), or futures contracts. While they can be volatile, their ability to retain value during inflationary periods makes them a crucial component of a diversified portfolio aimed at protecting against a 4% erosion in savings. Diversifying across different types of alternative assets can further mitigate risk.
Personal Budgeting and Debt Management
While investment strategies are crucial, effective personal budgeting and debt management form the foundational layer of defense against inflation. In an environment where prices are rising, controlling your expenses and minimizing high-interest debt becomes paramount. Every dollar saved on unnecessary spending or interest payments is a dollar that retains its purchasing power or can be strategically invested to outpace inflation. This personal financial discipline ensures that your income goes further and your financial stability remains intact.
Creating a detailed budget allows you to track your income and expenditures, identifying areas where you can cut back. Similarly, prioritizing the repayment of high-interest debts, such as credit card balances, frees up cash flow and reduces the amount of money lost to interest, which effectively acts as another form of erosion. These seemingly simple steps are powerful tools in your inflation-fighting arsenal, providing immediate and tangible benefits.
Strategies for Financial Resilience
Building financial resilience against inflation involves more than just investing; it requires a holistic approach to your personal finances. Prudent management of your daily spending and debt obligations can significantly strengthen your financial position.
- Create a Detailed Budget: Track all income and expenses to identify where your money is going and find opportunities to save.
- Reduce Discretionary Spending: Cut back on non-essential purchases to free up funds for savings and investments.
- Prioritize Debt Repayment: Focus on paying off high-interest debts first to minimize interest accrual and improve cash flow.
- Build an Emergency Fund: Maintain a robust emergency fund to cover unexpected expenses without resorting to high-interest loans.
By diligently managing your budget and debt, you create a stronger financial foundation that is more resistant to the pressures of inflation. This proactive approach not only protects your current savings but also enables you to allocate more resources towards investments that can help your wealth grow in real terms.
Long-Term Financial Planning for 2026 and Beyond
Protecting your savings from the projected 4% erosion in the US economy by 2026 requires a long-term perspective and a commitment to ongoing financial planning. Inflation is not a one-time event; it is a persistent economic force that demands continuous adaptation of your financial strategies. This involves regularly reviewing your investment portfolio, adjusting your budget, and staying informed about economic trends and policy changes. A static financial plan will inevitably fall victim to the dynamic nature of inflation.
Engaging with a qualified financial advisor can provide invaluable guidance, helping you to assess your risk tolerance, set realistic financial goals, and construct a portfolio that is resilient to inflationary pressures. Long-term planning also encompasses estate planning, retirement projections, and considering how inflation might impact future income needs. By taking a comprehensive and forward-looking approach, you can build a financial future that not only withstands inflation but thrives despite it.
Adapting Your Financial Strategy
Successful long-term financial planning against inflation involves flexibility and a willingness to adjust your strategies as economic conditions evolve. What works today might need modification tomorrow.
- Regular Portfolio Review: Annually or bi-annually, assess your investment performance against inflation and rebalance your portfolio as needed.
- Stay Informed: Keep abreast of economic news, central bank policies, and global events that could influence inflation rates.
- Consult Professionals: Work with financial advisors who specialize in inflation hedging and long-term wealth preservation.
- Educate Yourself: Continuously learn about different investment vehicles and strategies to empower your decision-making.
By integrating these practices into your financial routine, you transform from a passive observer to an active participant in managing your wealth. This proactive stance is essential for navigating the complexities of inflation and ensuring that your savings continue to grow in real terms, securing your financial future well beyond 2026.
| Key Strategy | Brief Description |
|---|---|
| Diversify Investments | Allocate funds across various asset classes like real estate, commodities, and TIPS to hedge against inflation. |
| Strategic Real Estate | Invest in properties or REITs for appreciation and rental income growth, which often keep pace with inflation. |
| Budget & Debt Management | Control expenses and repay high-interest debt to free up capital and reduce financial erosion. |
| Long-Term Planning | Regularly review and adjust financial plans, staying informed about economic trends and seeking professional advice. |
Frequently Asked Questions
A 4% inflation erosion means that the purchasing power of your money will decrease by 4% each year. For example, if you have $10,000, its real value will be equivalent to $9,600 after one year due to rising prices for goods and services.
The projected 2026 inflation is influenced by factors like global supply chain issues, past fiscal stimulus, geopolitical events, and energy price fluctuations. These elements combine to drive up the cost of production and consumer goods.
Real estate acts as an inflation hedge because property values and rental income tend to increase with rising prices. This allows your investment to appreciate in line with inflation, preserving and potentially growing your purchasing power over time.
Yes, precious metals like gold and silver are traditionally considered strong inflation hedges. They tend to retain their value during economic uncertainty and periods of high inflation, serving as a reliable store of wealth when fiat currencies lose purchasing power.
Budgeting is crucial during inflation because it helps you control rising expenses and prioritize essential spending. By managing your cash flow effectively and reducing unnecessary costs, you can free up funds to invest in inflation-resistant assets and maintain your financial stability.
Conclusion
The projected 4% inflation erosion by 2026 in the US economy presents a clear call to action for every individual keen on safeguarding their financial future. This is not a time for complacency but for proactive and informed decision-making. By understanding the underlying drivers of inflation, strategically diversifying your investment portfolio with assets like real estate and precious metals, and meticulously managing your personal budget and debt, you can build a robust defense against the erosion of your savings. Long-term financial planning, coupled with continuous learning and professional guidance, will be your most valuable tools in navigating this economic landscape. Taking these steps now ensures that your hard-earned money continues to work for you, preserving its purchasing power and securing your financial well-being for years to come.